Are townhomes a good fit for first-time buyers in NWA?
Often, yes – but it depends on the submarket. Entry-level townhomes in Rogers, Springdale, and parts of Fayetteville frequently sit at price points where FHA, VA, USDA, or conventional financing combined with ADFA down payment assistance of up to $15,000 can make ownership feasible earlier than a comparable detached home in Bentonville would. Downtown Bentonville luxury townhomes are not first-time buyer territory. The key step is matching the loan type to the right unit and confirming HOA dues fit comfortably inside the monthly budget alongside the mortgage payment.
What's the difference between a townhome and a condo, and why does it matter for my loan?
A fee-simple townhome means you own the land under the unit and the structure itself. Financing works the same way it would for a single-family home, with no project-level approval required. A condo-classified unit can look identical to a townhome from the outside, but legally you own interior airspace plus a share of common elements. FHA, VA, and most conventional loans require the entire condo project to be approved before any individual unit in it can be financed under that loan type.
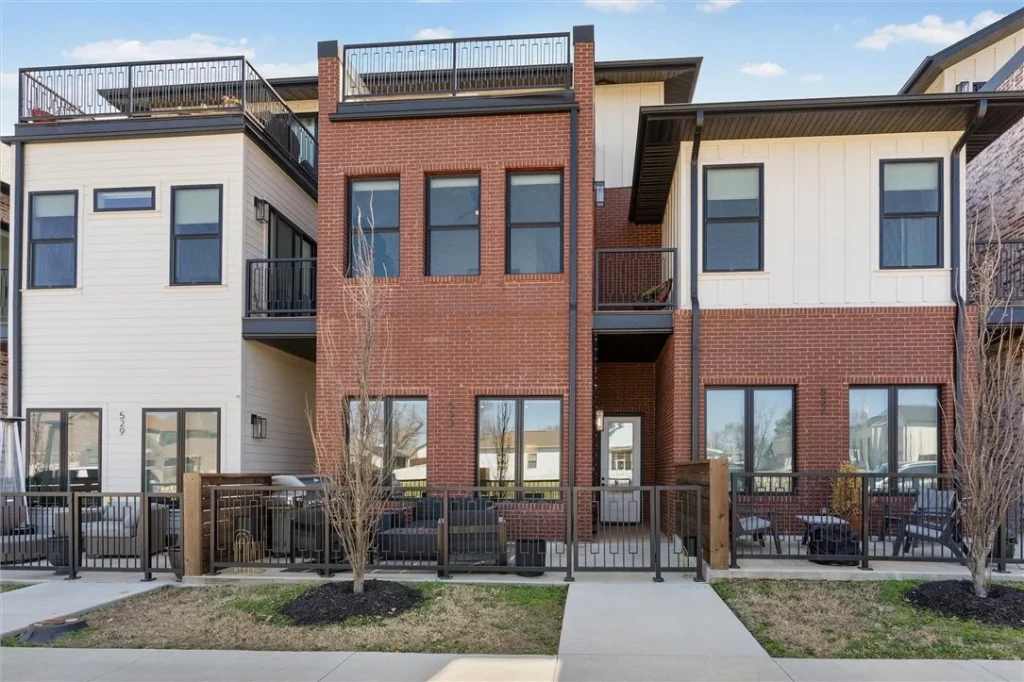
In NWA, several newer downtown Bentonville projects that present as townhomes are legally structured as condominiums. Confirming the classification before writing an offer prevents a financing dead-end mid-contract. The plat, the recorded declaration, and the title commitment are what give you the answer — not the marketing materials.
How much should I expect HOA dues to run on an NWA townhome?
Dues vary widely depending on what the association covers. A simpler HOA covering exterior maintenance, landscaping, and shared insurance may run a few hundred dollars per month. A higher-amenity downtown Bentonville HOA covering more services can run substantially higher.
Two questions matter more than the dollar figure itself. First, what does the dues amount actually cover: exterior maintenance, roof, insurance, water, trash, amenities? Second, are reserves funded well enough that a special assessment is unlikely in the next several years? Both answers come from the budget, the reserve study, and recent meeting minutes. These are documents Collier and Associates pulls and reviews during the offer or due-diligence phase, not after closing.
Can I use an FHA or VA loan to buy a townhome in NWA?
Yes, with one classification caveat. If the unit is fee-simple, both loan types treat it like a single-family home and no extra steps are required. If the unit is condo-classified, the project itself must be FHA-approved or VA-approved before that loan type can finance any unit in it.
Some downtown Bentonville projects are approved. Some are not. Some are working through approval. Confirming the project’s status with your lender is step one of the offer process for any condo-regime unit, and it’s a step that’s worth completing before you write an offer rather than after.
What are HOA red flags to watch for on an NWA townhome?
Several patterns warrant a closer look:
None of these is automatically disqualifying on its own. Each one changes the offer calculus and may justify a price adjustment, a longer due-diligence window, or walking away.
Are downtown Bentonville townhomes still being built, or has the wave passed?
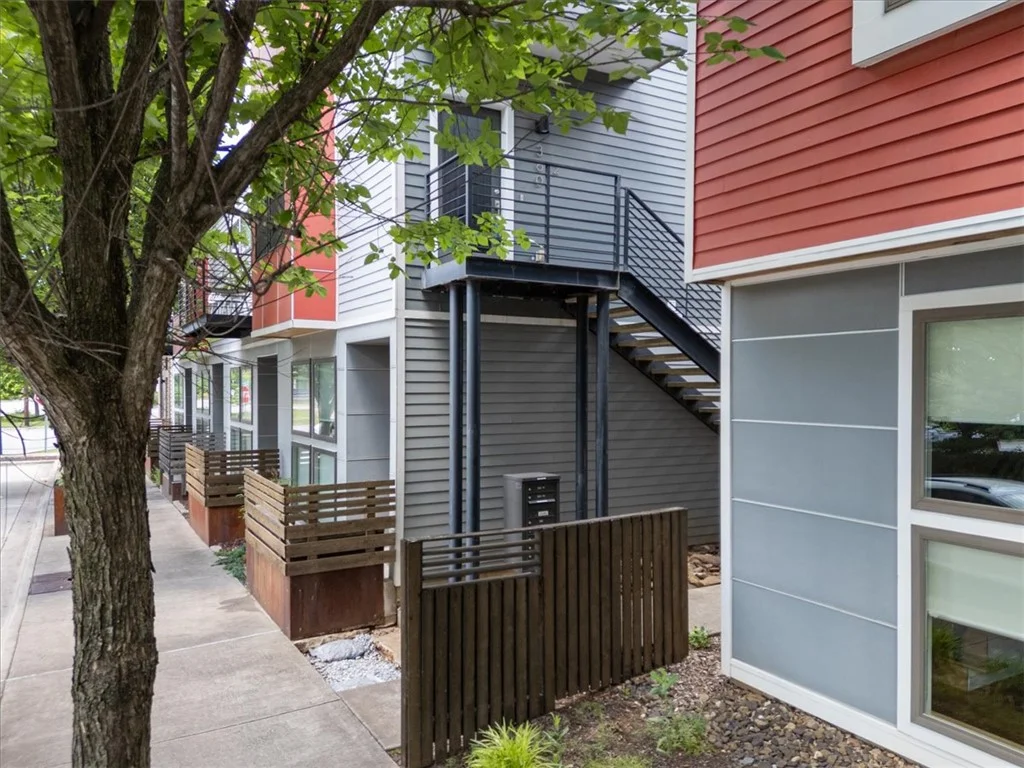
New attached projects are still being announced and built around downtown Bentonville and along the corridor near the Walmart Home Office. The mix is shifting toward higher price points and fewer entry-level attached units inside walking distance of the Square. For buyers priced out of downtown Bentonville, newer townhome construction continues at lower price points in Rogers, Centerton, and Springdale.